Last updated: September 10, 2026
Key Takeaways
- The term is 30 × 12 = 360 payments.
- Suppose the loan amount is $300,000, the rate is 6.0%, and the term is 30 years.
- Your principal-and-interest payment is about $1,799 per month.
- If annual property tax is $3,600, that adds $300 per month.
Table of Contents
- What this monthly payment actually includes
- How do I calculate monthly mortgage payment with taxes and insurance?
- Step by step: calculating the payment yourself
- What numbers should I gather before I calculate?
- When should I stop and get qualified help?
- The mistakes people make with taxes and insurance
- What changes when the standard formula does not fit?
A $2,000 mortgage payment can turn into $2,500 fast. Maybe more. The monthly mortgage payment with taxes and insurance is the principal and interest payment plus monthly property taxes plus monthly homeowners insurance, and sometimes mortgage insurance too. Break those pieces apart, and you can tell whether a lender’s estimate holds up—or whether the numbers are giving you the side-eye.
I’m writing this for someone who already has a loan amount, an interest rate, and at least a rough idea of annual property taxes and homeowners insurance. Missing those numbers? Fine. You can still follow the formula, but the result will only be a rough estimate. This is information, not financial advice; for your own situation, especially if you are comparing loan types or tax treatment across jurisdictions, consult a qualified adviser or financial professional. The Consumer Financial Protection Bureau and other official sources also recommend reviewing loan estimates and local tax and insurance documents before you rely on a monthly payment figure.
See: https://www.consumerfinance.gov/owning-a-home/estimate-your-monthly-payment/
What this monthly payment actually includes
Usually, people call the full monthly housing payment PITI: principal, interest, taxes, and insurance. “Principal” pays down the balance. “Interest” is the borrowing cost. “Taxes” usually means property tax billed by your local government. “Insurance” usually means a homeowners policy; if the lender requires mortgage insurance, that may also land in the monthly bill.
A lot of write-ups stop at principal and interest. That’s where the trouble starts. A $2,000 mortgage payment can become $2,500 or more once taxes and insurance are added, depending on where the property is and what coverage is required. Property tax rates, insurance premiums, escrow rules, and mortgage insurance rules vary by country, state, province, and lender, and they change over time.
Escrow is the key word here. That’s the account your lender may use to collect money each month for taxes and insurance and pay those bills when due. When a loan uses escrow, the quoted monthly payment often already includes those amounts. If it does not, you still owe the taxes and insurance, just on a separate schedule.
The math itself is straightforward. The trick is using the right inputs and keeping straight which figures are annual, monthly, or one-time. A generic “mortgage calculator” can be a decent starting point, but if you forget insurance or plug in the wrong tax bill, the answer can be off enough to matter. Ugly, honestly.
How do I calculate monthly mortgage payment with taxes and insurance?
Add three monthly pieces: principal and interest, property taxes, and insurance. If applicable, mortgage insurance goes in too.
A standard amortizing mortgage payment formula is commonly written as:
M = P × r × (1 + r)^n / ((1 + r)^n – 1)
where:
– M = monthly principal and interest payment
– P = loan amount
– r = monthly interest rate
– n = number of monthly payments over the full term
Say the annual interest rate is 6.0% on a 30-year loan. The monthly rate is 6.0% ÷ 12 = 0.5% per month, or 0.005 as a decimal. The term is 30 × 12 = 360 payments.
Then add:
– Monthly property tax = annual property tax ÷ 12
– Monthly homeowners insurance = annual premium ÷ 12
– Monthly mortgage insurance = annual premium ÷ 12, if your loan requires it
Lenders sometimes quote only principal and interest, especially if taxes and insurance are not in escrow. That is not the full housing cost.
Here’s a quick example. Suppose the loan amount is $300,000, the rate is 6.0%, and the term is 30 years. Your principal-and-interest payment is about $1,799 per month. If annual property tax is $3,600, that adds $300 per month. If annual homeowners insurance is $1,200, that adds $100 per month. Your total monthly payment is about $2,199 before any mortgage insurance.
Small changes matter. Even a slight shift in tax or insurance can move the monthly total by dozens of dollars.
Step by step: calculating the payment yourself
A spreadsheet works well, and a calculator does too if you are careful with decimals. I’d pick the spreadsheet, to be fair; it trims down the chance of a stupid arithmetic mistake.
- Write down the loan amount. Use the amount you will actually borrow, not the purchase price. For example, if the home costs $375,000 and you put down $75,000, the loan amount is $300,000. Verify that this matches the lender’s loan estimate. A common error is using the purchase price instead of the borrowed amount, which pushes the payment too high.
- Convert the annual interest rate to a monthly decimal. Divide the annual rate by 12, then divide by 100. A 7.2% annual rate becomes 0.072 ÷ 12 = 0.006 per month. Verify that you are using the note rate, not an advertised teaser rate. A common error is using the wrong rate or skipping the percent-to-decimal step, which breaks the formula.
- Count the total number of payments. Multiply years by 12. A 15-year mortgage has 180 payments; a 30-year mortgage has 360. Verify that the term matches the loan documents. A common error is mixing a 15-year term with a 30-year formula, which understates the payment.
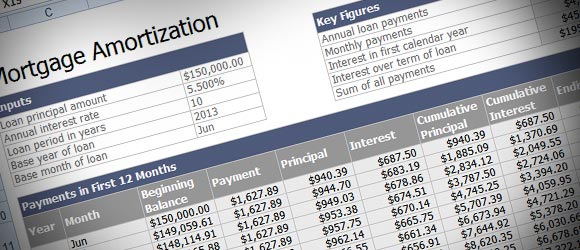
- Calculate principal and interest. Use the mortgage formula or a calculator. If you use a financial calculator or spreadsheet, check that the payment is monthly and that the result is positive. A common error is treating the result as annual instead of monthly, which makes the number meaningless.
- Find the annual property tax bill. Use the current tax bill if you have it, or the assessed tax estimate from the listing, county office, or lender. Divide that annual amount by 12. Verify whether the bill reflects the current owner’s exemptions; if it does, your future bill could be different. A common error is using a tax bill that includes an exemption you will not qualify for, which can leave you short each month.
- Find the annual homeowners insurance premium. Use a written quote or renewal amount, then divide by 12. Verify that the policy covers the same type of property and deductible you intend to carry. A common error is assuming a condo premium or a renter policy applies to a single-family home, which understates the cost.
- Add any required mortgage insurance. If the lender requires private mortgage insurance, lender-paid mortgage insurance, FHA mortgage insurance premium, or another equivalent charge, convert the annual amount to a monthly figure and add it. Verify whether it ends automatically or continues for the life of the loan. A common error is ignoring it because the loan estimate listed it separately, which makes the payment too low.
- Add the monthly pieces together. Principal and interest + monthly tax + monthly insurance + monthly mortgage insurance, if any. Verify the total against the lender’s Loan Estimate or payment schedule. A common error is forgetting one line item, which is the most common reason a payment looks smaller on paper than in real life.
If you want a spreadsheet formula, the monthly principal-and-interest part is often written with the PMT function. In Excel or Google Sheets, that might look like =PMT(rate/12, years*12, -loan_amount). You still need to add the tax and insurance pieces separately. For a built-in reference, Microsoft documents PMT here: https://support.microsoft.com/en-us/office/pmt-function-7c5ce1d6-5f2d-4a95-9f3a-0c73f0d8f43b
What numbers should I gather before I calculate?
Gather the loan amount, the note rate, the term, the annual property tax, the annual homeowners insurance premium, and any mortgage insurance amount before you do anything else. That’s the shortest route to a usable number.
A practical checklist is shown below.
| Item | Typical source | What it affects |
|---|---|---|
| Loan amount | Loan Estimate or mortgage documents | Principal and interest |
| Interest rate | Loan Estimate or mortgage note | Principal and interest |
| Property tax | Current tax bill or assessor records | Monthly escrow amount |
| Homeowners insurance | Written quote or renewal notice | Monthly insurance amount |
| Mortgage insurance | Loan Estimate or program rules | Monthly escrow amount or upfront cost |
The loan amount and rate usually come from the lender’s Loan Estimate or final mortgage documents, because those papers spell out the terms being offered. Property tax is usually pulled from the current county, municipal, or local tax bill or assessor records, though you should check whether exemptions will change after a sale. Insurance typically comes from a written quote by the insurer or broker that matches the actual property and coverage. If you are buying in a new development or a place with unusual assessments, ask whether there are HOA dues or special assessments too; those are not mortgage taxes, but they still affect your monthly housing cost.
There is a useful split between estimated and actual numbers. On a purchase, the seller’s current tax bill may reflect a different assessment history, a homeowner exemption, or a cap rule that will not apply to you. On an existing loan, an escrow analysis can change after a tax reassessment or insurance renewal. If you are using a listing, a tax website, or an online calculator, treat the result as a rough planning number, not a final payment.
One thing trips people up all the time: property taxes may be billed once a year, twice a year, or in installments. The payment formula still does not change. You convert the annual tax liability to a monthly amount by dividing by 12, even if the local bill shows up in two large chunks. That is how escrow works in most U.S.-style mortgage setups.
If you are comparing two homes with the same price but different tax bills, do not brush off the tax side. A $2,400 annual difference in property taxes changes the monthly payment by $200. Because of that, tax differences can affect debt-to-income ratios and affordability.
When should I stop and get qualified help?
Stop and get qualified help when the payment depends on tax law, insurance law, or loan terms you cannot verify from documents in hand. The calculation itself is simple; the inputs are where people get burned.
You do not have a written interest rate and term: the monthly principal-and-interest figure is guesswork — get the Loan Estimate, promissory note, or lender worksheet before you calculate.
The property tax bill includes an exemption you will not receive: your monthly tax escrow will be understated — ask the local assessor or a tax professional how the bill changes after transfer.
The home is a condo, co-op, or planned unit development: HOA dues, master insurance, or special assessments may sit outside the mortgage payment — add those separately and verify the ownership structure.
The loan includes FHA, VA, USDA, or similar program charges: mortgage insurance or funding fees may be handled differently from conventional loans — check the program rules and the lender’s estimate.
The insurance quote is for the wrong property type or coverage limit: the monthly insurance number will be misleading — get a quote that matches the actual dwelling and deductible.
You are relying on a refinance payoff or cash-out structure: closing costs, escrow setup, and new tax prorations can change the first several payments — ask the lender for an amortization schedule and escrow breakdown.
You are buying in a jurisdiction with unusual tax treatment or transfer taxes: the standard monthly formula will miss some ownership costs — consult a local tax adviser or real estate professional who knows the area.
That is also the moment to pause if you are using the payment as a substitute for a real budget. A lender’s payment is not the same as what you can comfortably afford after utilities, maintenance, repairs, or commuting costs. A mortgage can look fine on paper and still feel tight once the rest of life shows up.
The mistakes people make with taxes and insurance
The biggest mistake is calculating only principal and interest and calling that the mortgage payment. The result is predictable: the number looks affordable, then the escrow bill or insurance renewal arrives and the monthly cost jumps. The fix is to include taxes and insurance from the start.
Another common slip is using the seller’s current tax bill as if it were permanent. The result is an unpleasant surprise after reassessment or after a homeowner exemption disappears. The fix is to ask how the tax bill will change when the property changes hands.
People also misread insurance. They use an old premium from a previous property, or they forget that a higher-risk home, an older roof, or a lower deductible can change the price. The result is a monthly estimate that is too low. The fix is to use a quote tied to the actual property and coverage details.
A fourth error is forgetting mortgage insurance on low-down-payment loans. The result can be a payment gap big enough to affect approval or affordability. The fix is to confirm whether the loan has monthly mortgage insurance, a financed premium, or a one-time fee.
A fifth mistake is dividing by 12 when the figure is already monthly. The result is a tax or insurance amount that is understated by a factor of 12. Label every number before you add it: annual or monthly, not just a bare dollar amount.
A sixth error is comparing two loans only by rate. The result is that a slightly lower rate can hide higher insurance, taxes, or fees. Compare total monthly payment and total cash needed to close, not rate alone.
What changes when the standard formula does not fit?
The standard formula needs adjustment when the mortgage is not a plain fully amortizing loan with monthly payments. That happens more often than people think.
If the loan has an adjustable-rate mortgage structure, the payment can change after the initial fixed period. You can calculate the starting payment the same way, but do not assume it stays there for the full term. If the note says the rate adjusts after 5, 7, or 10 years, that is a real payment risk, not a rounding issue.
If the loan is interest-only for a period, the early payment is smaller because it does not reduce principal. That makes the usual amortizing formula wrong for that phase. You need the lender’s payment schedule, not a generic calculator.
If the mortgage insurance is paid as an upfront premium rather than monthly, the monthly payment may not include it, but the upfront closing cost still matters. Some programs roll that cost into the loan balance. That changes both the payment and the amount borrowed.
If taxes are billed semiannually or quarterly, the monthly equivalent is still annual tax divided by 12 for planning. Escrow does not care how the county bills you; it spreads the cost across the year. If your lender does not escrow, you need to set aside the money yourself on the same monthly basis.