Last updated: September 10, 2026
Key Takeaways
- Paying on day 1 usually helps more than paying on day 28, because fewer days of interest accrue on the old balance.
- A 6.5% fixed rate stays 6.5%; what changes is the base on which that 6.5% is charged.
- Which one happens depends on how your lender applies extra principal.
- I’m also assuming you want to understand the mechanics, not pick an investment.
A lump-sum payment usually changes amortization in one of two ways: it either shortens the loan term, or it reduces the next scheduled payment and leaves the term mostly intact. That’s the whole fork in the road. This article explains what happens to amortization when you make a lump-sum payment. Which one happens depends on how your lender applies extra principal. I’m writing this as information, not financial advice; for your own loan terms and tax situation, a qualified adviser is the right check.
Who this applies to, and what I’m assuming
This applies to anyone with an amortizing loan: a mortgage, auto loan, personal loan, or student loan that uses a fixed repayment schedule with interest and principal built into each payment. I’m assuming you already know your balance, interest rate, payment amount, and whether your loan has a prepayment penalty or any restriction on extra principal. Also, I’m assuming you want the mechanics, not an investment pitch. Simple enough.
An amortizing loan works by spreading the balance over a set number of payments. Early payments are mostly interest because interest is charged on the outstanding principal. Later payments shift toward principal because the balance is smaller. If you make a lump-sum principal payment — for example, an extra $2,000 or $10,000 — you reduce the balance immediately, and the interest calculation changes from that point forward.
That reduction does not erase past interest. It only changes the road ahead. On a 30-year mortgage, the lender may either recast the loan, which means recalculating the remaining payments after the extra principal is applied, or simply keep the same payment and let the loan end sooner. On many installment loans, the standard result is shorter amortization, not a smaller required payment. The contract decides this, not your preference.
This topic is not for someone who is already behind on payments and deciding whether to raid emergency savings to “catch up” without checking penalties, deferment options, or hardship terms. It is also not for someone with revolving debt such as a credit card; those balances do not amortize in the same way. If the loan has a prepayment fee, a balloon payment, or a negative amortization feature, the standard answer changes. No shortcuts there.
What amortization actually changes after a lump-sum payment
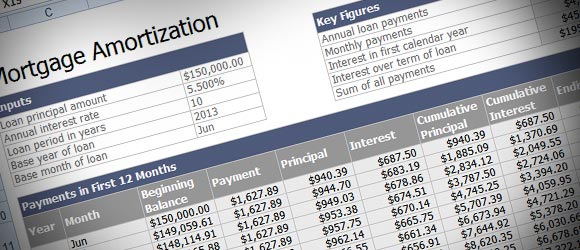
A lump-sum payment lowers the principal, and that changes the interest charged on every future payment. Amortization is just the schedule that shows how each payment is split between interest and principal over time. When the balance drops faster than planned, the schedule is no longer accurate unless the lender recalculates it.
Here is the core effect in plain terms:
- If the lender keeps your monthly payment the same, more of each future payment goes to principal, so the loan finishes earlier.
- If the lender recasts or reamortizes the loan, the payment is recalculated based on the new balance and remaining term, so your monthly amount may fall.
- If the lender treats the lump sum as a future-payment credit rather than principal reduction, the effect can be different; if you are unsure, check the statement or ask the servicer, because a loan professional can confirm how your lender posts it.
The technical term here is principal, meaning the amount you still owe before future interest. A lump-sum principal payment does not usually change the contract rate. A 6.5% fixed rate stays 6.5%; what changes is the base on which that 6.5% is charged.
A generic article often gets this wrong by saying “you save interest” without saying how. The useful version is more specific: you reduce the amount subject to interest for the remaining months. If you make a $5,000 principal payment on a loan that was scheduled to run for 120 more months, the interest savings come from 120 months of interest no longer being charged on that $5,000, but the exact amount depends on the rate, term, and posting rules. Do not assume the entire extra amount saves interest immediately if your lender posts payments in a different order. That math gets slippery fast.
A second point people miss: lump-sum principal payments usually do not affect the interest already accrued up to the payment date. If the loan accrues daily interest, the timing of the payment within the month matters. Paying on day 1 usually helps more than paying on day 28, because fewer days of interest accrue on the old balance, and the difference is easiest to confirm on your lender’s payoff or amortization statement. Timing matters. A lot.
How do I make sure the extra payment reduces principal?
You make sure by telling the lender to apply the money to principal and then confirming the next statement reflects a lower outstanding balance. The exact process varies by lender, but the steps below are the ones I would check in order.
- Read the note or loan agreement for prepayment language: look for “prepayment penalty,” “principal-only payment,” “recasting,” or “re-amortization” on the first 1–3 pages or in the payment section; verify whether extra money can be applied to principal without a fee; if the contract is silent or vague, that is a problem because the lender’s default posting rules may control.
- Ask how the lender posts extra funds: specify the payment amount and ask whether it will go to principal, next installment, or unapplied funds; verify the answer in writing if possible; a problem exists if the representative cannot explain whether your $1,000 will reduce balance or just cover future payments.
- Use the lender’s exact payment designation field: if there is a checkbox or memo line for “principal only,” “additional principal,” or “apply to principal,” use it; verify the confirmation screen before submitting; a problem exists if the platform forces the payment into the regular monthly bucket.
- Pay after the normal installment is current unless the lender says otherwise: keep the scheduled payment separate from the lump sum so the account is not marked short; verify the current installment remains fully paid; a problem exists if you send one combined amount and the servicer misapplies part of it.
- Confirm the posting date and cutoff time: ask for the business-day cutoff, often 4 p.m. or similar, and submit before it; verify the ledger date on the receipt; a problem exists if the payment posts the next day and extra interest accrues.
- Check the new principal balance on the next statement: compare the ending balance before and after the payment; verify that the balance dropped by the lump sum minus any interest already accrued; a problem exists if the balance barely changes, which can mean the money was treated as an advance payment.
- Ask whether the loan will be recast or simply shortened: a recast recalculates the remaining required payment, while a shortened amortization keeps the payment fixed and ends sooner; verify which outcome your lender uses; a problem exists if you expected lower payments but the lender leaves the payment unchanged.
- Keep the confirmation and statement together: save the receipt, screenshot, or mailed confirmation for at least the next 2 billing cycles; verify that each statement shows the extra principal applied; a problem exists if a later correction reverses the posting and you have no proof.
A good result looks boring: the balance drops on the statement, future interest charges decline, and the schedule either ends earlier or the payment is recalculated. A bad result is louder: the lender says the money is “held” or “applied to next payment,” and your principal barely moves. If that happens, stop and ask for a transaction-by-transaction ledger.
What happens to your payment schedule after the extra principal goes in?
Your payment schedule changes in proportion to how the lender handles the balance, and that change can be small or dramatic. If the lender does not recast, the scheduled payment stays the same and the loan matures sooner. If the lender does recast, your payment drops because the remaining balance is smaller, but the maturity date may stay close to the original term. Either way, the amortization table has to be rebuilt from the date the lump sum posts.
The standard term of art here is recast, sometimes called re-amortization. That means the lender takes the new balance and spreads it over the remaining months, often after a fee or under specific loan rules. Recasting is common in some mortgage servicing arrangements and less common in many auto or personal loans. Not every lender offers it, and not every loan permits it.
A useful way to think about it is this: a lump sum can change either the height of the monthly step or the length of the staircase. If the loan is fixed-payment and not recast, the staircase gets shorter. If it is recast, each step may get lower. The total interest paid over the remaining life usually falls either way, but the monthly cash flow outcome differs.
The trade-off is simple. Shortening the term usually saves more interest than recasting to a lower payment, because you keep paying at the original pace. But lower monthly payments can matter more if cash flow is tight, especially for someone carrying multiple obligations. I would consider the lower-payment route only if the budget needs room and the loan terms make recasting inexpensive or automatic. It is not the fastest route if your goal is to finish the debt as fast as possible.
One detail people miss: an extra principal payment made near the start of the loan has a larger effect than the same payment made near the end. That is not a slogan; it is how amortization works. On an early schedule, a bigger share of future payments would have been interest on a larger balance. On a late schedule, much of that interest is already behind you. The front end is where the juice lives.
What are the mistakes that mess this up?
The most common mistakes are simple, and each one changes the result in a concrete way.
-
Sending a lump sum without principal instructions.
The consequence is that the payment may be applied to a future installment instead of principal, which leaves the amortization schedule almost unchanged. The correct alternative is to use the lender’s principal-only designation and confirm it in writing. -
Assuming every extra dollar reduces balance immediately.
The consequence is disappointment when daily interest or posting delays eat part of the benefit. The correct alternative is to ask for the posting date, cutoff time, and accrued interest rules before sending the money. -
Mixing the regular payment and the extra principal in one ambiguous transfer.
The consequence is misapplication, short-payment notices, or a delayed principal credit. The correct alternative is to separate the scheduled installment from the lump sum if the lender’s process allows that. -
Ignoring prepayment penalties or fees.
The consequence is that the fee can absorb some or all of the interest saved, especially on smaller extra payments. The correct alternative is to check the note for penalty language and compare the fee with the likely benefit before acting. -
Expecting a lower monthly payment when the loan will only shorten.
The consequence is budget confusion because the required installment stays the same. The correct alternative is to ask in advance whether the lender recasts, and if so, whether there is a minimum extra-payment threshold such as a specific balance level or dollar amount. -
Forgetting tax and insurance effects on mortgages.
The consequence is thinking the monthly payment fell when only the principal-and-interest portion changed; escrow for property tax and homeowners insurance may stay the same. The correct alternative is to compare the full mortgage payment with the principal-and-interest line separately.
These mistakes are especially common when people hear “extra payment” and treat all loans the same, so it helps to check the contract or talk with a loan professional before sending money. A mortgage, an auto loan, and a student loan can have different posting rules, forgiveness rules, or federal protections. Rates, tax treatment, and penalties differ by country and change over time, so any real decision should be checked against the current loan documents, local rules, and a qualified adviser.
When should you stop and get the loan terms checked?
You should stop and get the terms checked whenever the loan has a clause that changes how extra principal is treated, because those clauses can override the usual amortization result.
There is a prepayment penalty: the fee can reduce or wipe out the value of the lump sum — calculate the penalty and the remaining interest before paying more.
The loan is a mortgage with a servicing rule you do not understand: the servicer may hold or misapply funds — ask for the written principal-only process and confirm the next statement.
The loan uses daily interest and the payment date is late in the cycle: a delay can add extra interest — move the payment date earlier or ask how the cutoff works.
The loan is in deferment, forbearance, or hardship status: extra principal may not work the way you expect — confirm whether payments are even being applied to principal at this time.
The loan has a variable rate or reset clause: the interest rate may change later, which affects the value of shortening the term — review the reset schedule before deciding.
The account is delinquent or in collections: the servicer may apply funds to fees or arrears first — prioritize curing the account and get the allocation order in writing.
The contract allows recasting but charges a fee: the fee changes the math — compare the fee with the monthly payment reduction and the remaining term.
For mortgages and student loans especially, a qualified financial or legal adviser can help you interpret the contract without guessing. That is the cheapest way to avoid an expensive posting error.
What if the loan is not a plain fixed-rate mortgage?
The standard answer changes when the loan is not a plain fixed-rate amortizing loan, and that is where people get into trouble. On an adjustable-rate mortgage, the future payment is already scheduled to change with the rate reset, so the effect of a lump sum depends on timing. On a loan with negative amortization, the minimum payment may be less than the accrued interest, so a lump-sum principal payment may only slow the balance growth. On a balloon loan, the amortization schedule ends with a large final payment, so a lump sum can reduce that balloon, but only if the contract permits principal reduction before maturity.
Student loans can be even messier because servicers may apply extra payments in a specific order, and federal or private loan rules differ. Some auto loans allow principal-only payments with no recast, while others don’t. So the same cash can behave very differently. Funny, but true.