Last updated: September 10, 2026
Key Takeaways
- In a 30-year mortgage with monthly payments, that means 360 lines.
- Add an extra $50 or $100 principal payment and see whether the payoff date moves.
- Input principal, APR, term, and payment frequency, such as $18,000 at 8.9% for 72 months.
- Example: a 1% origination fee on a $250,000 mortgage is $2,500.
Amortization tools and comparisons answer one thing very well: how a loan balance falls over time, and how much of each payment goes to interest versus principal. That is the whole point. If you are weighing a mortgage, auto loan, student loan, or business loan, this is the question to answer before signing anything. This guide shows how amortization tools and comparisons work, what they show, and how to choose the right one.
Table of Contents
- Who this guide is for, and what you need to already know
- What an amortization tool actually shows
- Which amortization tools should you compare?
- How do I compare amortization tools without getting fooled?
- What makes one amortization tool better than another?
- Common mistakes people make with amortization comparisons
- When the standard amortization approach does not apply
Who this guide is for, and what you need to already know
Borrowers comparing loans, checking a payment schedule, or deciding whether extra payments are worth it are the people this guide is for. You should already know the basics: principal is the amount borrowed, interest is the cost of borrowing, and term is the length of the loan, such as 36 months, 15 years, or 30 years. Honestly, I am assuming you want a better choice, not a prettier spreadsheet.
Amortization is the repayment pattern built into a loan. In a standard amortizing loan, the payment stays fixed, but the split changes over time: early on, most of it goes to interest; later, more of it chips away at principal. Many mortgages, auto loans, and personal loans work that way. Not all products do. A credit card can revolve with a variable balance; a balloon loan can leave a large payment at the end; an interest-only loan delays principal repayment. Different animals.
For high-stakes borrowing, an amortization tool is not there to “find the best deal” in some fuzzy sense. It is there to compare total cost, cash flow, and risk. Adjustable rates, prepayment penalties, deferred interest, negative amortization, and balloon payments can all trip up a basic calculator unless you know what got left out. Negative amortization means the balance can rise if the payment does not cover all interest due. Ugly stuff. And it changes the math.
I would use a simple amortization schedule for a plain fixed-rate loan with no odd clauses. I would slow down, or get the lender’s full disclosure, before trusting a tool when the loan includes an introductory rate, a rate cap, or an early-payoff penalty. The usual loan estimate or truth-in-lending disclosure should tell you enough to model the loan more honestly, and Consumer Financial Protection Bureau guidance on Loan Estimates explains the disclosure you should review. If the agreement is unclear, the tool is not the problem; the contract is.
What an amortization tool actually shows
An amortization tool shows how each payment is split and how the balance falls, month by month or per payment. The real value is not the final balance alone. It is the path from today to payoff, because that path tells you how much interest you will pay, how much equity or ownership you build, and how sensitive the loan is to extra payments.
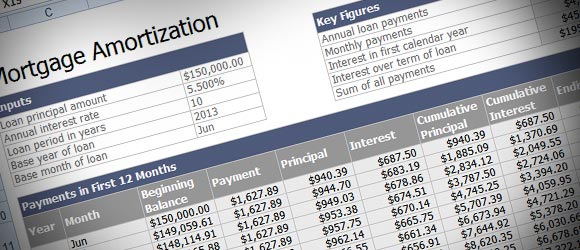
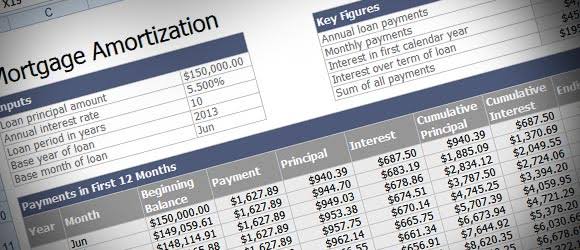
The core output is an amortization schedule. Usually, a schedule lists payment number, payment date, payment amount, interest portion, principal portion, and remaining balance. In a 30-year mortgage with monthly payments, that means 360 lines. In a 5-year auto loan, 60 lines. A tool may also show totals: total interest paid over the life of the loan, total principal repaid, and sometimes an early payoff date if you add extra principal.
Interest is charged on the unpaid balance. That is the engine. Early in the loan, the balance is large, so interest takes a bigger slice of each payment. Later, the balance shrinks, so principal takes over. This is why extra principal payments tend to matter most when they are made early. A $100 extra payment in year 1 often saves more interest than the same $100 in year 9 of a 10-year loan. The exact savings depend on the interest rate and remaining term.
A good tool also shows the effective cost of waiting. If a loan is 6% fixed for 60 months, the amortization schedule gives you a useful picture of the trade-off: lower required payment now versus more interest over time. If the rate is variable, the schedule is a projection, not a promise. I would treat that projection as a scenario, not as fact, and the Consumer Financial Protection Bureau’s materials on adjustable-rate mortgages are a useful place to check how resets work. That matters a lot on mortgages tied to an index like SOFR or on business loans that reprice periodically.
And there is the part people often ignore. A calculator may leave out origination fees, closing costs, taxes, insurance, required escrow, or prepayment penalties. Those are not part of pure amortization, but they change the real cost. A fee-free spreadsheet can make two loans look closer than they are. If one loan has a 1% origination fee and the other has none, that fee can outweigh a small rate difference on a short term.
Which amortization tools should you compare?
Compare tools by the questions you need answered, not by the polish on the screen. A simple calculator, a spreadsheet, and a lender’s own estimator each have a different job. The right pick depends on whether you need a quick answer, a detailed schedule, or a side-by-side look at two or more loans.
A basic online amortization calculator is fine for a fixed-rate loan with one payment amount, one term, and no odd features. It usually asks for principal, APR, term, and payment frequency. That is enough to estimate monthly payments on a $25,000 car loan at 7% over 60 months or a $300,000 mortgage at 6.5% over 30 years. Fast. Clean. A little too tidy, sometimes.
A spreadsheet, such as Excel or Google Sheets, is better when you want control. You can add extra payments, skip certain months, change the interest rate, or compare two loans side by side. If you know the PMT, IPMT, and PPMT functions in Excel, you can build a schedule that is more transparent than many web calculators. Excel and Google Sheets both can do this well, provided the formulas are set up carefully.
A lender or servicer calculator may reflect the contract more closely, especially for loans with special terms. If you are comparing mortgages, the lender’s disclosure documents and payment estimate may include escrow, mortgage insurance, or rate-adjustment rules. That makes them useful for checking what you actually owe. The downside is obvious: the lender’s tool is usually built to make that lender’s product look its best.
A comparison tool or loan-comparison template is useful when you are choosing between different APRs, terms, and fees. APR, or annual percentage rate, is supposed to reflect the loan’s yearly cost including certain fees, not just the note rate. Even so, APR can hide cash-flow differences. A 48-month loan and a 72-month loan can have very different monthly payments and total interest, even if the APR looks close. So I would compare at least three things: monthly payment, total interest, and total cash outlay including fees.
For a quick decision, I would start with a calculator. For a serious decision, I would move to a spreadsheet or a lender disclosure and build a side-by-side table. If the loan has a floating rate, I would compare at least two scenarios: the current rate and a higher rate that fits the cap or worst-case adjustment allowed in the contract. On an adjustable-rate mortgage, that can mean comparing the initial payment with the fully indexed payment, not just the teaser rate. The CFPB and Fannie Mae both explain why mortgage disclosures and payment scenarios matter when terms are not fixed.
How do I compare amortization tools without getting fooled?
You compare amortization tools by testing the same loan terms in each one and checking whether they handle the same features. If they do not accept the same inputs, they are not really comparable. A tool that cannot model extra principal, irregular payments, or variable rates may still be useful, but only for a narrow kind of loan.
Start with the input fields. A serious tool should let you enter principal, interest rate, term, payment frequency, start date, and extra payment amount. If it handles taxes, insurance, escrow, or fees, that is a bonus for mortgage comparison, not a necessity for every loan. The more advanced tools may let you choose monthly, biweekly, weekly, or semimonthly payments. That matters because payment frequency affects how quickly principal falls. Biweekly payments can accelerate payoff in a standard amortizing loan because you make the equivalent of one extra monthly payment per year, but only if the lender applies payments the way you expect.
Then compare the outputs. You want at least these three: payment amount, total interest, and payoff date. If two tools disagree on any of those, do not assume one is “wrong” right away. First check whether one includes fees, whether one rounds differently, and whether one applies payments at the beginning or end of the period. Small rounding choices can move the final balance by a few cents; a bad payment convention can twist interest over a long term.
Next, test edge behavior. Add an extra $50 or $100 principal payment and see whether the payoff date moves. Change the rate by 1 percentage point and see whether the schedule responds properly. If the tool is built well, the interest burden should rise materially with the rate and fall with extra principal. If it barely changes, something is off.
Here is the step-by-step method I would use.
- Enter the core loan terms exactly. Input principal, APR, term, and payment frequency, such as $18,000 at 8.9% for 72 months. Verify: the calculated payment is plausible for that rate and term. Problem sign: a monthly payment that seems far too low or far too high usually means the rate, term, or frequency is entered incorrectly.
- Check whether the tool assumes monthly compounding. Many consumer loans compound monthly, but some consumer finance products and business loans use daily interest or another convention. Verify: the loan disclosure states the compounding method or the tool lets you choose it. Problem sign: if the tool gives a payment that conflicts sharply with the lender’s quote, the compounding method may be the reason.
- Add fees separately if they are not built in. Include origination fees, closing costs, document fees, and required insurance where relevant. Example: a 1% origination fee on a $250,000 mortgage is $2,500. Verify: the comparison includes both note rate and upfront fees. Problem sign: a loan with a lower APR but high fees may look cheaper than it really is.
- Model at least one extra-payment scenario. Add a fixed extra principal amount, such as $100 or $250 per month, and keep the scheduled payment unchanged. Verify: the payoff date shortens and total interest falls. Problem sign: if the balance does not change faster, the tool may be applying the extra payment to interest, not principal.
- Test a rate change if the loan is variable. Raise the rate by 1 to 2 percentage points or use the contract’s adjustment cap. Verify: the new payment or interest total shifts in the expected direction. Problem sign: if the schedule ignores the adjustment, it is not suitable for an adjustable-rate loan.
- Check the first and last line of the schedule. Confirm the first payment date, first interest amount, and remaining balance after the final payment. Verify: the final balance reaches zero or near zero because of rounding. Problem sign: a nonzero residual balance, especially above a dollar, suggests rounding or formula errors.
- Compare total cost over the same horizon. If one tool shows a 60-month loan and another shows a 72-month loan, normalize them to the same term or same payoff date. Verify: you are comparing like with like. Problem sign: a longer term can hide a lower monthly payment behind much higher total interest.
- Save or export the schedule. If the tool allows CSV, PDF, or spreadsheet export, save it before you make the decision. Verify: you can inspect the numbers later. Problem sign: if you cannot reproduce the result, you cannot audit the loan later.
This is where the comparison becomes useful. A good amortization tool should not just output a payment; it should let you see how a $75 extra payment, a 0.5% rate difference, or a 12-month term change alters the path to payoff. If it cannot show that, it is only a calculator, not a comparison tool.
What makes one amortization tool better than another?
The better tool is the one that matches the loan’s complexity and your decision. For a plain fixed-rate loan, simplicity wins. For a mortgage with escrow or an auto loan with an odd fee structure, detail wins. I would not rank tools by “most features” alone, because more knobs can also mean more chances to misuse the tool.
A strong consumer calculator handles at least four inputs cleanly: loan amount, rate, term, and payment frequency. It should show the payment formula clearly enough that you can tell whether you are comparing APR or note rate. It should not force you to guess what happens to extra principal. If it does, that extra payment may be reducing future scheduled payments rather than shortening the loan, which is a different result.
A strong spreadsheet template earns its keep by being auditable. I want to see each cell’s logic, a clear start date, and formulas that carry through to the end of the term. Change the rate from 6.25% to 6.75%, and the whole schedule should update without breaking. Add a $150 monthly prepayment, and the payoff date should move forward automatically. Excel and Google Sheets both can do this well, but only if the formulas are set up carefully.
A strong lender estimate is useful because it reflects the contract. That matters most for mortgages and auto loans where the actual amount due can include taxes, fees, insurance, and escrow. But a lender estimate is not neutral. Its job is to describe that lender’s offer, not to compare the market fairly. If the estimate omits a relevant fee, ask for the loan estimate or equivalent disclosure in writing.
I also care about whether the tool handles payment timing properly. Some tools assume every payment occurs at the end of the month. Others let you choose beginning-of-period payments, which are common in leases or annuities. In a standard loan, payment timing should match the contract. A one-period timing mismatch can slightly change interest math, and over 30 years that difference becomes noticeable.
My rule is simple: use the least complicated tool that still models the loan you actually have. If you are comparing two fixed-rate 48-month car loans, a basic calculator plus a spreadsheet note on fees is enough. If you are comparing a 30-year mortgage with a 5/1 adjustable-rate mortgage, I would use a fuller model because the payment path matters more than the first quoted monthly number.
Common mistakes people make with amortization comparisons
The most common mistake is comparing monthly payment only. A lower monthly payment can hide a longer term and much more interest. A 72-month auto loan can look easier than a 48-month loan because the payment is lower, but the total cost can be far higher. The correct alternative is to compare monthly payment, total interest, and total paid over the same horizon.
The second mistake is ignoring fees. A loan with a lower rate but a $3,000 fee may be worse than a slightly higher-rate loan with no fee, especially on a short term. The correct alternative is to include upfront costs in the comparison or at least calculate the break-even period. If you plan to keep the loan only 24 months, a long break-even period can kill the deal.
The third mistake is treating APR as the only answer. APR is useful, but it is not magic. It does not always capture every real-world cost, and it does not tell you how cash flow feels month by month. The correct alternative is to use APR as one filter and then check the schedule itself. For mortgages, the payment plus escrow can be more important than APR alone.
The fourth mistake is not matching payment timing. A biweekly payment plan can reduce interest if each payment is applied when expected, but some lenders simply collect two half-payments and credit them monthly. The consequence is slower payoff than promised. The correct alternative is to verify how the lender applies payments before assuming the tool’s payoff date is real.
The fifth mistake is assuming extra principal always helps in the same way. On a loan with a prepayment penalty, extra payments can trigger fees. On a loan with a payment recast feature, extra principal may reduce the required payment rather than shorten the term. The correct alternative is to read the loan terms and decide whether your goal is lower payment or faster payoff.
The sixth mistake is trusting rounded schedules too far. If a tool rounds each month too aggressively, the balance may drift. The consequence is a small but annoying mismatch between the calculator and the lender’s statement. The correct alternative is to use a tool that carries enough decimal precision and accept tiny residuals due to rounding, especially on long terms