Last updated: September 10, 2026
Key Takeaways
- Check the loan term first, such as 30 years or 360 months.
- For a borrower with steady income, this setup can work well; the trade-off is the tighter timing of a half-payment every 14 days.
- Here’s the basic yardstick: 26 biweekly half-payments equal 13 monthly payments in a year, which is why payoff time usually drops.
- When a lender treats 14-day payments as early partials, speak with a mortgage professional or servicer first and review the note plus the payment-allocation rules, because the payoff effect can be reduced or delayed.
Biweekly mortgage payments usually shorten the life of a 30-year mortgage because you make 26 half-payments a year, which adds up to 13 full monthly payments instead of 12. That extra payment goes to principal reduction, so the balance falls sooner and interest has less time to pile up. Not financial advice. For your own situation, a qualified mortgage adviser or loan officer should check your note, servicer rules, and any fees first.
Who this applies to, and what has to be true first
A borrower with a standard installment mortgage fits this best, especially a fixed-rate loan with a 15-, 20-, or 30-year term, and especially if they are thinking about paying every two weeks instead of once a month. You also need the basics in hand: the interest rate, remaining balance, payment due date, and whether your servicer allows partial payments or biweekly allocation.
The core idea is simple; the paperwork is not. A mortgage note says how payments get applied, and a servicer’s billing system may or may not accept true biweekly posting. Some lenders offer a formal biweekly program, while others simply let you make extra principal payments on your own. Not the same animal. A formal program may charge setup or processing fees; the informal route may cost nothing but leaves you to manage the schedule yourself.
Stable cash flow matters here. This method is best for a borrower who can handle the slightly tighter timing of a half-payment every 14 days. It is a poor fit if your budget is already thin, if your paychecks arrive monthly, if your lender charges for every extra transaction, or if your loan has prepayment penalties. Honestly, I’d be careful if you are carrying high-interest debt or have no emergency fund, because the mortgage is not the only number on the page.
A useful benchmark: 26 biweekly half-payments equal 13 monthly payments in a year, which is why payoff time usually falls. That does not mean the reduction is identical for every loan. The effect depends on how the lender credits the extra amount and whether the first payment starts immediately or waits until the next scheduled due date.
How biweekly mortgage payments change the payoff date
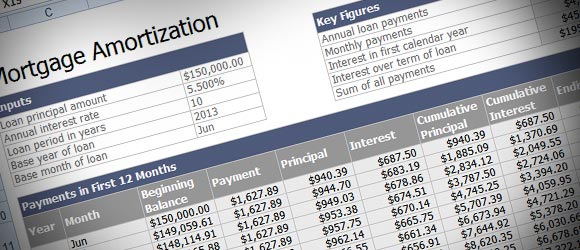
Biweekly payments shorten payoff time because they create one extra monthly payment each year without changing the loan’s interest rate or amortization formula. “Amortization” is the schedule that splits each payment between interest and principal over the life of the loan. Early on, more of each payment goes to interest; later, more goes to principal. Add one extra principal reduction each year, and the balance shrinks faster, so future interest is charged on a smaller amount.
Two payment patterns make the difference clear:
- Monthly schedule: 12 full payments a year.
- Biweekly schedule: 26 half-payments a year, which equals 13 full payments.
That one extra payment can shave years off a long mortgage, but the exact payoff reduction depends on the interest rate, original term, remaining balance, and whether the servicer applies each half-payment as soon as it arrives. If the lender simply holds the first half-payment until the full monthly amount arrives, the payoff effect is weaker. If the lender posts each payment immediately to principal and interest, the reduction is stronger. Plain and simple.
The trap is thinking the benefit comes from the word “biweekly” itself. It does not. The benefit comes from paying the equivalent of one extra monthly payment per year. A borrower who makes one extra principal payment annually, even without switching to biweekly billing, can often get a similar payoff result. That is why the payment structure matters less than the actual cash flow into principal.
I would not treat a biweekly plan as automatic savings. If the lender charges enrollment fees, per-payment fees, or a required escrow service fee, those costs reduce the benefit. If your mortgage has a small remaining balance or a very low rate, the payoff gain may be modest. The method tends to matter most on long-term loans, especially 30-year fixed mortgages with many years left; see the Consumer Financial Protection Bureau’s mortgage payment guidance at https://www.consumerfinance.gov/consumers/ for general payment-application questions.
How do you calculate the payoff difference?
Compare your current monthly schedule with a biweekly schedule that results in 13 full payments per year, then check how the lender applies each payment. Base the comparison on your actual loan balance, not a generic example, because small changes in rate or remaining term can move the payoff date noticeably.
Here is the procedure I would use:
- Write down the loan facts exactly as shown on your statement. Record the outstanding principal balance, interest rate, next due date, and whether escrow is included. Check the loan term, such as 30 years or 360 months. If the statement does not clearly show how extra payments are applied, that is a problem because the payoff estimate may be wrong.
- Ask the servicer how extra principal is credited. You need to know whether a payment above the scheduled amount is applied immediately to principal or held for the next due date. Ask for the servicer’s payment allocation rules in writing. If the answer is vague, the problem is usually the servicing system, not your math.
- Convert the monthly payment into two half-payments. Divide the scheduled principal-and-interest payment by 2, then note that 26 half-payments equal 13 full payments per year. Make sure this is not the same as sending one-half of a payment every month; that would not create the same acceleration. If the lender requires the full monthly amount before crediting the loan, the biweekly plan may not work as intended.
- Compare annual cash outflow under both methods. Under the monthly schedule, you pay 12 installments. Under the biweekly schedule, you pay 26 half-payments. The problem to watch for is any fee that makes the 26-payment system more expensive than simply making one extra principal payment each year.
- Check whether the extra amount is applied to principal only. The goal is to reduce the balance, not to prepay interest. Verify that any extra money beyond the scheduled amount is marked “principal only” if your servicer allows that designation. If not, the payment may be posted in a way that blunts the payoff benefit.
- Look for fees in the program terms. Many biweekly services charge setup fees, monthly maintenance fees, or transaction fees. Even a small recurring fee can offset part of the interest savings. If the fee schedule is unclear, the issue is not the payoff math but the cost of the program.
- Project the new payoff date using an amortization calculator or the lender’s payoff quote. The figure you want is the remaining months to zero balance under both schedules. Verify that the calculator uses the same posting frequency you plan to use. A mismatch in compounding or payment timing can produce a misleading result.
- Confirm there is no prepayment penalty. Some loans, especially certain older or nonstandard loans, can penalize early principal reduction. If a prepayment charge exists, it can erase much of the advantage. If you cannot confirm this from your note, that is a sign to review the documents carefully before changing the schedule.
A quick conceptual check helps: if your plan creates the equivalent of 13 full payments each year and the servicer credits them properly, the loan should pay off sooner than the original term. If it does not, something is off in the posting rules, the fee structure, or the way the payments are being sent.
What actually shortens the loan, and what does not?
The extra principal payment shortens the loan; the label “biweekly” does not. That distinction matters because many borrowers think the calendar cadence itself creates savings. It does not. Only money that reaches principal earlier than scheduled changes the amortization path.
Interest savings come from reducing the principal balance sooner. On a fixed-rate mortgage, interest is calculated on the outstanding balance. If that balance drops earlier in the year, the next month’s interest charge is lower than it would have been on a standard schedule. Over many years, that effect compounds. If your loan has 20 or more years left, the payoff-date change can be meaningful. If you are already late in the amortization schedule, the benefit will be smaller because much of the interest has already been paid.
There is also a difference between a true biweekly payment plan and a self-managed extra payment plan. A true biweekly plan may split the monthly payment and post each half as received. A self-managed plan often means you keep making monthly payments but send one extra principal payment annually or make a half-payment every two weeks on your own. Both can accelerate payoff if the extra funds are applied correctly. The second route often gives you more control and fewer fees.
What does not help as much as people think? Simply sending the mortgage payment every 14 days if the lender treats those payments as early partials and leaves them unposted until the full amount arrives. In that case, the money may sit in suspense rather than reducing principal sooner. That is why the posting rules matter more than the calendar; see Freddie Mac’s consumer mortgage payment resources at https://myhome.freddiemac.com/ for general servicing and payment-posting questions.
I’d be skeptical of any claim that biweekly payments are a magic trick. They are a budget discipline tool. If the discipline is strong and the fees are low, the payoff date usually moves up. If the fees are high or the payment processing is clumsy, the benefit shrinks fast.
When should you not use a biweekly mortgage plan?
You should not use it when the payment structure creates more cost, more risk, or less flexibility than a plain monthly mortgage payment. That is especially true on high-stakes debt, where a small administrative mistake can take months to unwind.
Your servicer charges recurring transaction fees: The extra cost can eat into or exceed the interest savings — Stick with monthly payments and make occasional principal-only payments instead if your budget allows.
Your mortgage has a prepayment penalty: Early principal reduction may trigger a fee — Review the note and ask the servicer for the exact penalty terms before changing anything.
Your income is irregular or paid monthly: Half-payments every 14 days can strain cash flow — Stay with the monthly due date so you do not create a late-payment problem.
You have high-interest consumer debt: Extra mortgage principal is less flexible than paying off a 20% credit card balance or building an emergency reserve — Stabilize short-term finances first, then revisit the mortgage.
Your loan is near payoff already: The remaining interest savings may be small — A biweekly conversion may not justify the administrative hassle or fees.
The servicer cannot clearly explain payment posting rules: If they cannot tell you how extra funds are credited, the payoff estimate is uncertain — Request written terms or use another method that you can track yourself.
These are not theoretical objections. They are the spots where a neat-sounding plan turns into paperwork trouble or a budget headache. If any of them apply, I would slow down and read the note before sending extra money.
The mistakes people make with biweekly payments
The most common mistake is assuming every biweekly plan creates the same payoff result. It does not. The consequence can be years of disappointment if the servicer merely holds funds or charges for the privilege. Better move: confirm posting rules and use principal-only extra payments when possible.
A second mistake is starting biweekly payments without checking escrow. Escrow covers taxes and insurance, and it is usually part of the monthly mortgage bill. Split the bill incorrectly, and you can end up underpaying the escrow portion or confusing the servicer’s ledger. The alternative is to separate the principal-and-interest portion from escrow and confirm exactly what should be split.
A third mistake is sending half-payments at the wrong interval, such as twice a month instead of every two weeks. That sounds similar, but it is not. Twice monthly means 24 half-payments a year; biweekly means 26. The consequence is a smaller acceleration effect. The fix is simple: use a 14-day cadence, not a calendar-month cadence.
A fourth mistake is forgetting about fees. Some formal programs advertise convenience but charge enough to reduce the benefit, especially on smaller balances. The alternative is to compare the fee schedule against the value of the extra principal reduction before enrolling.
A fifth mistake is treating the mortgage as the only goal and ignoring liquidity. If your cash reserves are thin, locking extra money into principal can make it harder to handle repairs or job loss. The correct alternative is to keep a separate emergency buffer before accelerating a mortgage.
A sixth mistake is not verifying whether the extra payment is truly principal-only. If the servicer misapplies the payment, your payoff date may not move as expected. The correction is to label the payment clearly and check the next statement for how it was credited.
What changes when the loan is not a standard 30-year fixed?
The standard advice needs adjustment for adjustable-rate mortgages, balloon loans, interest-only periods, and mortgages with irregular payment rules. Those products can change the payoff math in ways that biweekly timing alone will not fix.
With an adjustable-rate mortgage, the rate can reset, so the effect of extra principal depends on both today’s rate and future rate changes. Biweekly payments still reduce principal faster, but the payoff benefit is harder to forecast. If you are near a reset date, I would be careful about relying on a long-range estimate.
With an interest-only mortgage, extra payments can matter a great deal because they are often the only way principal declines before the interest-only period ends. But the lender’s terms matter even more. You want to verify how extra money is credited during the interest-only window.
With a balloon mortgage, the main risk is not payoff time but the lump sum due at maturity. A biweekly schedule may reduce the balance, but it does not automatically solve the balloon obligation. The note controls the outcome, and the maturity date matters more than the calendar cadence.
With FHA, VA, USDA, or other government-backed loans in the United States, and with comparable programs in other countries, the payment rules can vary by insurer, guarantor, or local regulation. Because mortgage rules differ by country and change over time, I would not assume a payment pattern from one market applies in another without checking the loan documents and the servicer’s