Last updated: September 10, 2026
Key Takeaways
- That is why the same $200 can have very different effects depending on where it goes.
- Suppose a borrower has a 30-year mortgage at 7% and makes an extra principal payment each month.
- If the borrower instead refinances into a 30-year loan at 6%, the payment may drop, but the lender also resets the amortization schedule.
- Recalculate with a higher rate for the refinance, a smaller extra payment, or a shorter holding period by 12 months.
A borrower with the wrong timing can spend money in the wrong place. Plain and simple.
If your only goal is to cut mortgage interest, extra principal payments usually save more per dollar than refinancing does. But refinance can still win when your current rate is high enough, your loan term is long enough, and the closing costs are low enough to be recovered before you move or pay off the loan. Honestly, that trade-off is where a lot of people get tripped up.
This is general information, not financial advice. Mortgage rules, rates, fees, and tax treatment vary by country and change often, so a qualified adviser should look at your own loan, income, and tax situation before you act. For a basic overview of mortgage amortization and refinancing costs, see the CFPB’s mortgage resources and your local housing authority or tax agency before deciding.
Who this applies to — and what you need in hand first
This applies to a homeowner who already has a mortgage and wants to know whether to reduce interest by changing the loan or by sending extra money to the lender. I am assuming you know your current balance, interest rate, remaining term, and whether your loan has prepayment penalties, a cash-out feature, or refinance fees attached to it. You do not need to be a math person, but you do need the numbers from your mortgage statement and, if you are considering a refinance, at least one written loan estimate.
The core difference is straightforward: a refinance replaces the loan, while extra payments chip away at the balance you already owe. A refinance can lower your rate, shorten your term, or both. Extra payments leave the rate alone; they shrink principal faster, which means less interest gets charged on what remains. Same $200. Different outcome.
Not every borrower gets the same answer. A borrower with a 7.5% fixed-rate loan and 27 years left may get a very different answer from someone with a 3.25% loan and 18 years left. I would also draw a hard line around a few situations that need professional review before you decide: adjustable-rate mortgages, loans with prepayment penalties, government-backed loans with special rules, and any refinance that would roll closing costs into the balance. Those are not automatic deal-breakers, but they change the math enough that guessing is a bad idea. For details on loan estimates and fee disclosure, see the CFPB and your lender’s official estimate form.
What saves more interest: refinance or extra payments?
Extra payments usually save more interest per dollar than refinancing because every dollar goes straight to reducing principal. A refinance only saves more if the rate drop is large enough and the refinance costs are low enough that the lower payment outweighs those costs over the time you keep the loan. That math stops working fast if the fees are heavy.
Here is the logic without pretending there is one universal winner. Suppose a borrower has a 30-year mortgage at 7% and makes an extra principal payment each month. That extra principal reduces the balance immediately, so the next month’s interest is charged on a smaller amount. Now flip the setup: if the borrower refinances into a 30-year loan at 6%, the payment may fall, but the lender also resets the amortization schedule. Amortization means the way each payment is split between interest and principal over time. A lower rate helps, but restarting the clock can blunt the savings if you were already several years into the old loan.
A refinance tends to make sense when three things line up: the new rate is meaningfully lower, you expect to keep the loan long enough to recover fees, and the new term does not stretch the payoff date too far. Extra payments tend to make sense when the current rate is already decent, you want certainty, and you care about total interest more than monthly payment relief.
A generic article often misses the most important trap: people compare the new monthly payment with the old monthly payment and stop there. That comparison ignores closing costs, any new term length, and the fact that extra payments save interest on the exact day they are made. If you are deciding strictly on interest saved, the question is not “which payment is smaller?” It is “how much principal gets retired sooner, and what does that cost me?” On a 30-year loan, even a small shift in principal timing can matter a lot over 20 or 25 years, but that does not mean refinancing is always worse. It means you have to compare total cost, not just the headline rate. See your loan amortization schedule and, if needed, ask a mortgage professional to check the assumptions.
How do I compare them without guessing?
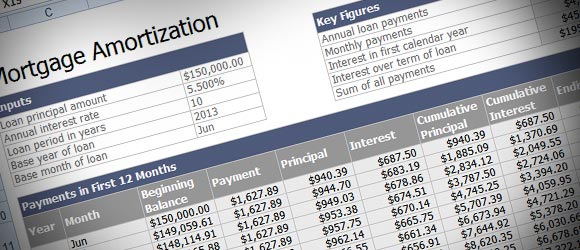
Line them up on the same horizon, the same balance, and the same all-in cost, then see which route leaves less interest behind. I would do it in a spreadsheet or with an amortization calculator from a lender, bank, or government-backed housing agency, and I would check both the monthly result and the total interest over the period you expect to keep the home.
- Write down the current loan facts. Gather the outstanding balance, interest rate, remaining term in months, payment amount, and whether the loan has a prepayment penalty. Verify all five items on your latest statement; if any number differs from the statement, the comparison is already wrong.
- Get the refinance terms in writing. Ask for a loan estimate that shows the new rate, term, monthly payment, and all upfront closing costs. Verify whether the costs are paid out of pocket or added to the loan; if they are rolled in, the balance increases and the interest savings shrink.
- Choose one time horizon. Use the period you actually expect to keep the mortgage, such as 5 years, 7 years, or until payoff. Verify that both options are measured over the same horizon; if one scenario runs 30 years and the other runs 5 years, the comparison is meaningless.
- Model the extra payment as principal-only. Enter an additional monthly or annual payment and make sure it is applied to principal, not to future scheduled payments. Verify the lender’s allocation rules; if the lender simply advances your next due date, the interest savings may be smaller than expected.
- Include refinance break-even. Divide refinance closing costs by the monthly savings, if any, to estimate how many months it takes to recover fees. Verify that the break-even point is earlier than your expected holding period; if not, the refinance may reduce interest on paper but not in your real timeline.
- Check the total interest paid, not just the monthly payment. Compare cumulative interest over the same horizon. Verify that the refinance does not add so much time back onto the loan that the lifetime interest goes up even though the rate is lower.
- Run a second version with a shorter payoff date. Test what happens if you refinance into a shorter term, such as moving from 30 years to 15 or 20 years, versus making the same extra payment amount. Verify whether the shorter term still fits your cash flow; if the payment becomes tight, the “saving” is theoretical only.
- Stress-test the decision. Recalculate with a higher rate for the refinance, a smaller extra payment, or a shorter holding period by 12 months. Verify whether the choice is still better under slightly worse conditions; if the answer flips easily, you are at a margin where fees or timing matter more than the rate headline.
A good result is not “the lowest monthly payment.” A good result is the lower total interest burden over the time you will actually own the loan. For some borrowers, that means refinancing to a shorter term. For others, it means keeping the loan and sending $100, $300, or $500 extra to principal each month. The amount matters less than the discipline and the accounting.
Should I refinance if I can make extra payments instead?
I would treat refinancing as a rate-and-term change and extra payments as a balance-reduction strategy, then compare them on the same cash amount. If the refinance costs several thousand dollars and the extra-payment plan uses the same monthly dollars directly against principal, extra payments often win on pure interest savings.
The reason is structural. An extra principal payment starts saving interest immediately and carries no new closing cost. A refinance may lower the rate, but it also creates new fees such as appraisal charges, title work, origination charges, and recording fees, depending on your market and lender. Those fees are real cost, even if they are wrapped into the loan balance. If you never recover them through lower interest, the refinance did not save money overall. For fee categories and closing-cost disclosures, check the CFPB and your loan estimate.
There is one case where refinance can beat extra payments: when the current rate is high enough that the rate drop is large, and the borrower will keep the loan long enough to cross the break-even point. For example, a homeowner with a high-rate mortgage and a long expected stay may save more by moving to a materially lower rate than by sending modest extra principal each month. But the larger the rate gap, the more the numbers matter and the more the new term matters too. A refinance into a fresh 30-year term can lower the payment while still leaving a lot of interest in place. That is why a lower monthly payment is not the same thing as a lower interest bill.
This is also where the tax question sometimes appears. In many places, mortgage-interest deductibility is limited, changed often, and highly specific to the borrower and property. I would not let a possible deduction decide this comparison without tax advice, because the deduction does not erase the underlying cost of interest. For country-specific rules, consult a tax professional or your local revenue authority.
When should I stop and ask for qualified help?
You should stop and get qualified help when the mortgage has features that change the payoff math or the legal terms of the new loan. The following situations are the ones I would not treat as simple do-it-yourself comparisons, so a mortgage adviser, lender, or housing counselor should review them before you decide.
Adjustable-rate mortgage with a pending reset: the rate can change on a schedule, often tied to an index and margin, so today’s comparison may age badly — get a refinance or payment strategy reviewed before the reset date.
Prepayment penalty in the current note: extra principal could trigger a fee that erases part of the interest savings — ask the lender to quote the penalty in writing before making large extra payments.
Cash-out refinance: if the new loan includes extra borrowing beyond the payoff amount, the interest comparison is no longer apples to apples — separate the debt-consolidation question from the mortgage question and get advice.
Very early payoff goal, such as 2 to 3 years: refinance closing costs may never be recovered in that short window — use a break-even analysis and have a professional check the figures.
Income instability or a tight debt-to-income ratio: a lower payment can look attractive, but a refinance can also create underwriting hurdles or extend your dependence on debt — do not use payment relief as the only measure of success.
Government-backed or special-program loan: FHA, VA, USDA, and some local programs can have fee structures or eligibility rules that change the answer — confirm the rules with the program materials and a qualified adviser.
Planned sale, relocation, or inheritance timing: if the home may be sold before the refinance break-even point, or the mortgage may be paid off from another source, the cheaper-looking option may not stay cheaper — match the decision to the real exit date.
The consequence in each case is the same: the wrong comparison can make you think you are saving on interest when you are actually paying fees, extending debt, or losing flexibility. When the structure is unusual, I would rather see a borrower slow down for a day than save the wrong amount on the wrong metric. The Consumer Financial Protection Bureau and your loan servicer can help confirm the fee structure and payoff rules.
The mistakes that make the wrong option look better
The most common mistake is comparing monthly payments instead of total interest. That can make a refinance look better simply because the payment drops after the term resets, even when the borrower pays more interest over time. The correct alternative is to compare cumulative interest over the same holding period.
Another mistake is ignoring closing costs. A refinance with a lower rate can still be worse if the fees take too long to recover or are rolled into the loan balance. The correct alternative is to treat those costs as part of the decision, not an afterthought.
A third mistake is sending extra money without specifying principal-only treatment. Some lenders apply extra funds to the next scheduled payment instead of reducing principal immediately. The consequence is delayed interest savings. The correct alternative is to confirm the lender’s application rules and label the payment clearly.
A fourth mistake is choosing a refinance because the monthly payment fits the budget, then stretching the term from, say, 20 years back to 30. The consequence is paying interest for longer. The correct alternative is to compare a new loan term against the time left on the current mortgage, not against the old monthly bill alone.
A fifth mistake is forgetting about prepayment penalties or refinancing restrictions. The consequence can be a fee or loan condition that wipes out months of savings. The correct alternative is to read the promissory note and loan disclosures before making a move.
What changes the answer in real life?
The answer changes when the mortgage balance is small, the remaining term is short, or the rate gap is tiny. In those cases, a refinance often has too little runway to recover its costs, while extra payments still reduce principal immediately. If you have only a few years left on the loan, every closing fee matters more.
The answer also changes if you already have a low fixed rate. With a rate in the low single digits, refinancing just to “improve” the loan often makes little sense unless the structure of the new loan is materially better for another reason. Extra payments may be the cleaner way to reduce interest because they do not disturb a favorable loan.
On the other hand, if your current loan is expensive and you can refinance into a lower rate without extending the term too much, the refinance can reduce interest faster than modest extra payments. This is especially true when the old loan still has many years left. A rate drop on a large balance over a long horizon can do a lot of work.
A special case is biweekly payments. Biweekly is not magic. In some setups it simply accelerates principal because you end up making the equivalent of 13 monthly payments a year; in others the servicer’s rules determine whether the extra amount is applied correctly. I would check the servicer’s treatment before assuming any savings. The same caution applies to automatic round-up programs and one-time annual lump sums.
How long does the choice take to pay off?
The choice can pay off in months or in many years, but the decisive factor is the break-even point on the refinance side and the compounding effect on the extra-payment side. A refinance may start lowering the monthly bill right away, yet still need 18, 24, or 36 months before the closing costs are fully recovered. Extra payments start cutting interest immediately, but the visible payoff can feel slower because the monthly payment usually does not fall.
That timing difference is why the holding period matters so much. If you plan to stay in the home for 2 years and the refinance break-even is 30 months, the refinance is probably not the better interest-saving move. If you plan to stay for 10 years and the break-even is 14 months, the refinance may make more sense. I would keep the comparison tied to the real exit date, not a theoretical best case. For an official explanation of break-even and amortization, see the CFPB mortgage tools and your lender’s estimate.
If the main goal is faster payoff, extra payments generally work better because each dollar directly shortens the balance. If the main goal is lower monthly strain with some interest reduction, a refinance can do more for cash flow, especially when rates are meaningfully lower. The trade-off is that cash flow relief can come with longer total interest unless the new structure is tight.
What is the bottom line?
The bottom line is that extra payments usually save more mortgage interest per dollar, while refinancing usually helps more with monthly payment relief. If you want the answer in one line, compare the total cost over the time you expect to keep the loan, including refinance fees and any change in term.
If the refinance rate drop is large, the fees are low, and you will stay in the home long enough to clear break-even, refinance can be the better interest move. If not, extra payments are usually cleaner, cheaper, and easier to undo if your circumstances change. In either case, use your actual numbers, not a rule of thumb, and check the loan estimate, amortization schedule, and any tax or program rules before you decide.
If you want, I can also turn this into a calculator-style worksheet or a shorter decision tree you can use with your own loan numbers.