Last updated: September 10, 2026
Key Takeaways
- Most mortgages accrue interest daily using a 365-day year, though some contracts use actual/360 or another convention.
- Example structure only: principal × annual rate ÷ 365 = daily interest.
- Ask for a final payoff update if closing moves by even 1 day.
- A mortgage at 6% on a $300,000 balance accrues about $49 per day on a 365-day basis, before any fees.
Refinancing? Start with the payoff statement, not the online balance. That’s the blunt truth. How calculate mortgage payoff after refinance is never just your current mortgage balance; the figure is the exact amount the lender says must land on the closing date to wipe out the old loan, and it often folds in principal, accrued interest, and sometimes fees or escrow adjustments.
Table of Contents
- Who this applies to, and what you need in hand
- How do you calculate the mortgage payoff amount after refinance?
- What changes the payoff amount the most?
- What mistakes do people make when they estimate a payoff?
- When should you stop calculating it yourself?
- What if the refinance is closing at the end of the month?
- How long does the payoff process take, and what should the final number look like?
- Common questions I hear about refinance payoffs
Mortgage rules, fees, and tax treatment vary by country and lender, so I would check your lender’s payoff statement and speak with a qualified adviser about your own situation before you sign anything. For U.S. borrowers, the CFPB explains mortgage payoff statements and related servicing rules; for UK borrowers, the FCA sets mortgage servicing expectations.
Who this applies to, and what you need in hand
How calculate mortgage payoff after refinance applies when you are swapping one mortgage for another and need the amount that has to be wired to close the old loan cleanly. You need three things in hand: your current loan number, your latest mortgage statement, and a proposed refinance closing date. Without those, you can guess — but you cannot calculate with confidence.
It also assumes a standard amortizing mortgage, not a reverse mortgage, a construction loan, or a loan already in default. Those situations can bring different payoff rules, prepayment penalties, or servicing arrangements, and the math shifts. If your loan sits in foreclosure, bankruptcy, a modification trial, or a shared-equity program, stop there and get qualified help; the number may not be straightforward at all.
The number that matters is the payoff statement. That written quote from the lender shows the exact amount needed to retire the loan on a specific date. Your online balance is only the unpaid principal. It usually leaves out daily interest, and it may also miss late charges, reconveyance costs, recording charges, or a per-diem interest rate. Per-diem interest means the daily interest charge on the loan.
A lot of generic explainers miss one annoying detail: the payoff changes with the date. On a refinance, even a one-day shift in closing can move the amount. So the date on the payoff statement matters just as much as the dollar figure. Maybe more.
How do you calculate the mortgage payoff amount after refinance?
Start with the unpaid principal, then add daily interest through the planned payoff date, then fold in any lender-approved fees or escrow adjustments that belong on the payoff statement. The lender or servicer should give you the exact number, but you can get close if you know the loan terms.
Here is the process I would actually use:
- Pull the current unpaid principal balance from the latest statement. Use the line labeled principal balance, not the total amount due. Verify the statement date and the loan number. If the figure already includes interest billed earlier, you are looking at the wrong line.
- Find the note rate and the daily interest method. Most mortgages accrue interest daily using a 365-day year, though some contracts use actual/360 or another convention. Verify the loan documents or the payoff statement. If the servicer cannot tell you the method, your estimate may be off by several dollars per day.
- Request a payoff statement for the exact refinance closing date. Ask for the payoff good through a specific date, such as the scheduled closing date. Verify whether the statement is good through that date only. If the refinance closes after the quoted date, the amount can be stale.
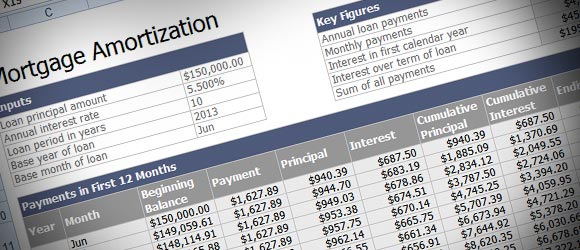
- Calculate accrued interest to the payoff date. Multiply the daily interest charge by the number of days from the last interest-paid date to the payoff date. Example structure only: principal × annual rate ÷ 365 = daily interest. Verify whether your loan counts the day of payoff, the day after, or both. If you include the wrong day count, your estimate will be short or high.
- Add any contractual charges listed by the servicer. These can include a late fee, a reconveyance fee, a recording fee, or a statement fee, depending on the loan and jurisdiction. Verify each fee against the payoff statement. A fee that appears without explanation should be questioned before closing.
- Check whether escrow funds are included or excluded. Escrow is the account that holds taxes and insurance. Some payoff statements include an escrow refund later; others do not fold it into the payoff amount at all. Verify with the servicer and your closing agent. If escrow is handled twice, the wire amount can be wrong even when the payoff figure is correct.
- Compare the payoff statement to the refinance closing disclosure. The old loan payoff on the new loan’s closing documents should match the lender’s quoted payoff amount for the same date. Verify the numbers line by line. If they differ, one document is using a different date or a different fee assumption.
- Ask for a final payoff update if closing moves by even 1 day. Many servicers require a refreshed statement near funding. Verify the expiration date on the quote. If the quote has expired, do not assume it is still accurate.
For a rough estimate, use this:
Payoff amount ≈ current principal balance + accrued daily interest + lender fees
Useful? Yes. Final? No. The exact figure can still shift because of partial payments, suspense accounts, late fees, or interest that keeps running after the last statement date. A suspense account is money the lender has received but not yet applied to principal or interest.
I would treat a self-calculated payoff as a planning tool, not the figure you wire, and I would confirm the final amount with the servicer or a qualified adviser before funding. The lender’s written payoff statement wins. For mortgage payoff statements and servicing timing, see the CFPB and your local regulator.
What changes the payoff amount the most?
Closing date, plain and simple. Interest adds up every day, and a mortgage at 6% on a $300,000 balance accrues about $49 per day on a 365-day basis, before any fees. I’m not treating that as a universal number; it’s just a clean example of how fast the total can move.
Recent payment timing matters next. If you made your last payment on the 1st and the payoff happens on the 18th, the lender will usually collect interest only through the 18th, not through the full monthly cycle, but the exact handling depends on the loan contract and the servicer’s method. That’s where people trip over the paperwork: they assume a monthly payment schedule means a monthly payoff schedule. Nope.
Escrow can also change the cash needed at closing, and in some cases it can affect the payoff figure itself. Some refinance closings include enough money to fund the old loan payoff and set up the new escrow account. Others leave escrow refunds to be mailed later. That is why the payoff amount and the total cash-to-close are not the same thing.
Prepayment penalties, if your loan has them, are separate again. These are charges for paying the loan off early. Not every mortgage has one, and the terms vary by country, state, lender, and loan type. If your note has a penalty clause, the payoff statement should show it clearly. If it does not, do not assume there is none; check the promissory note and ask the servicer.
Finally, a payment posted after the statement cut-off or sitting in suspense can make the balance look lower or higher than expected. That is one reason a payoff quote should come straight from the servicer, not from the portal. Check your mortgage statement and the CFPB’s payoff guidance for the date and interest method the servicer uses. The wrong day count is a sneaky little gremlin.
What mistakes do people make when they estimate a payoff?
Using the loan balance as though it were the payoff is the most common mistake. The result is a shortage at closing, which can slow funding or force a same-day correction. The correct alternative is to use the lender’s payoff statement for the actual closing date.
Daily interest gets forgotten a lot. The result is usually a wire that comes up short by one or more days of interest, which is enough to leave the old loan open. The correct alternative is to count the days from the last paid-through date to the payoff date using the lender’s stated interest method.
Small fees get brushed aside because they look harmless. A $25 statement fee or a reconveyance charge may not sound like much, but it still belongs in the payoff total if the lender includes it. The correct alternative is to verify every fee on the payoff statement and ask whether each one is required by contract or local practice.
An outdated payoff quote is another trap. Mortgage payoffs usually expire quickly, often on a date tied to the quote. If closing slips by even 1 business day, the amount can change. The correct alternative is to get a refreshed statement whenever the closing date moves.
Cash to close gets mixed up with payoff amount too. Cash to close can also include title charges, prepaid interest on the new loan, escrow deposits, and taxes. The result is underfunding the settlement. The correct alternative is to separate the old-loan payoff from the rest of the refinance worksheet and compare it with the closing disclosure.
When should you stop calculating it yourself?
Stop and bring in the servicer, closing agent, or a qualified adviser when the loan has features that can bend the payoff math in ways a standard estimate will miss.
Your loan is in default, forbearance, or foreclosure: the payoff can include legal fees, inspection charges, or accelerated amounts — do not rely on a normal amortization estimate.
The mortgage has a prepayment penalty clause: the payoff can jump by a contractual charge — ask for the exact payoff statement and the note language.
You made a recent extra principal payment or partial payment: the servicer may hold money in suspense or apply it differently — verify how the payment was posted before you estimate.
The closing date changed after the payoff quote was issued: the quote may have expired or the interest may have advanced — request a new payoff statement.
You have a second mortgage, HELOC, or home equity line tied to the refinance: each lien has its own payoff rules and may need separate statements — do not combine them into one number.
The loan is adjustable-rate, interest-only, or negatively amortizing: the standard principal-plus-interest estimate may not match the actual payoff — have the servicer explain the exact payoff formula.
The servicer and the closing agent are using different dates: even a 1-day mismatch can change the amount — align the date before funding.
These are not “maybe later” problems. They are the spots where a simple worksheet stops being trustworthy. If you see any of them, do not try to muscle through the math alone.
What if the refinance is closing at the end of the month?
The payoff amount usually includes interest only through the payoff date, but the cash you need at closing can be affected by month-end timing, holiday cutoffs, and how the lender counts the day of funding. End-of-month closings are where confusion tends to pile up, because people mix up per diem interest, monthly payment dates, and escrow billing cycles.
If closing is on the 28th, 29th, 30th, or 31st, I would ask for a payoff statement that is valid through that exact date and then confirm wire cutoff times. Many lenders and title companies require wires before a bank deadline, often in the afternoon, and a missed cutoff can push the closing to the next business day. That can change the payoff by another day of interest.
This is also where monthly mortgage statements are least helpful. A statement may show the next payment due on the 1st, but the refinance payoff might need to stop interest on the 22nd or 24th. Different numbers, different job. The statement balance is not a settlement number.
Holiday weekend? Then the extra days matter. I would verify the servicer’s business-day rules rather than assuming calendar days are counted the same way everywhere. Mortgage servicing departments do not all use the same cutoff rules, and those rules can vary by lender and country. A borrower who is short by even one day of interest may not get a clean payoff confirmation until the shortfall is cured. That one day can bite.
How long does the payoff process take, and what should the final number look like?
The payoff request itself can be prepared quickly, but the full refinance payoff process usually takes several coordination steps between the servicer, title company, and closing agent. I would expect the written payoff statement to name the loan number, payoff good-through date, per diem interest amount, principal balance, and any fees line by line. If those items are missing, the statement is incomplete.
A solid payoff number is specific, dated, and explainable. It should not look like a random round figure. It should show why the balance is what it is on that day. If the number changes, the lender should be able to point to the daily interest or the fee that caused the change.
For a quick sanity check, compare three figures: the unpaid principal balance, the estimated accrued interest, and the final payoff statement. If the payoff is dramatically higher than those together, ask why before sending money. A one-time collection of taxes or insurance is not usually part of the old mortgage payoff; if it appears, you need the lender to explain it.
For reference, mortgage servicing rules and borrower rights are often discussed by national consumer finance regulators such as the Consumer Financial Protection Bureau in the United States and the Financial Conduct Authority in the United Kingdom. Those organizations are worth checking if your country uses similar servicing standards, but the exact rules still depend on local law and your loan contract.
Common questions I hear about refinance payoffs
The payoff amount is not the same as the mortgage balance, and that is the part most people miss. Here are the questions that come up most often:
Can I calculate it from my online account?
You can estimate it, but not rely on it. Online balances often omit per diem interest, fees, or posting delays.
Does the old lender keep my escrow money?
Usually not forever, but the handling varies. Some escrow balances are refunded after payoff; others are netted differently at closing.
What if my refinance funds after the payoff date?
The payoff usually increases by another day or more of interest. You need an updated statement.
Is the payoff amount what I bring to closing?
Not always. The payoff is one piece of cash to close. The refinance can also require taxes, prepaid interest, and title charges.
**Should I ask for the